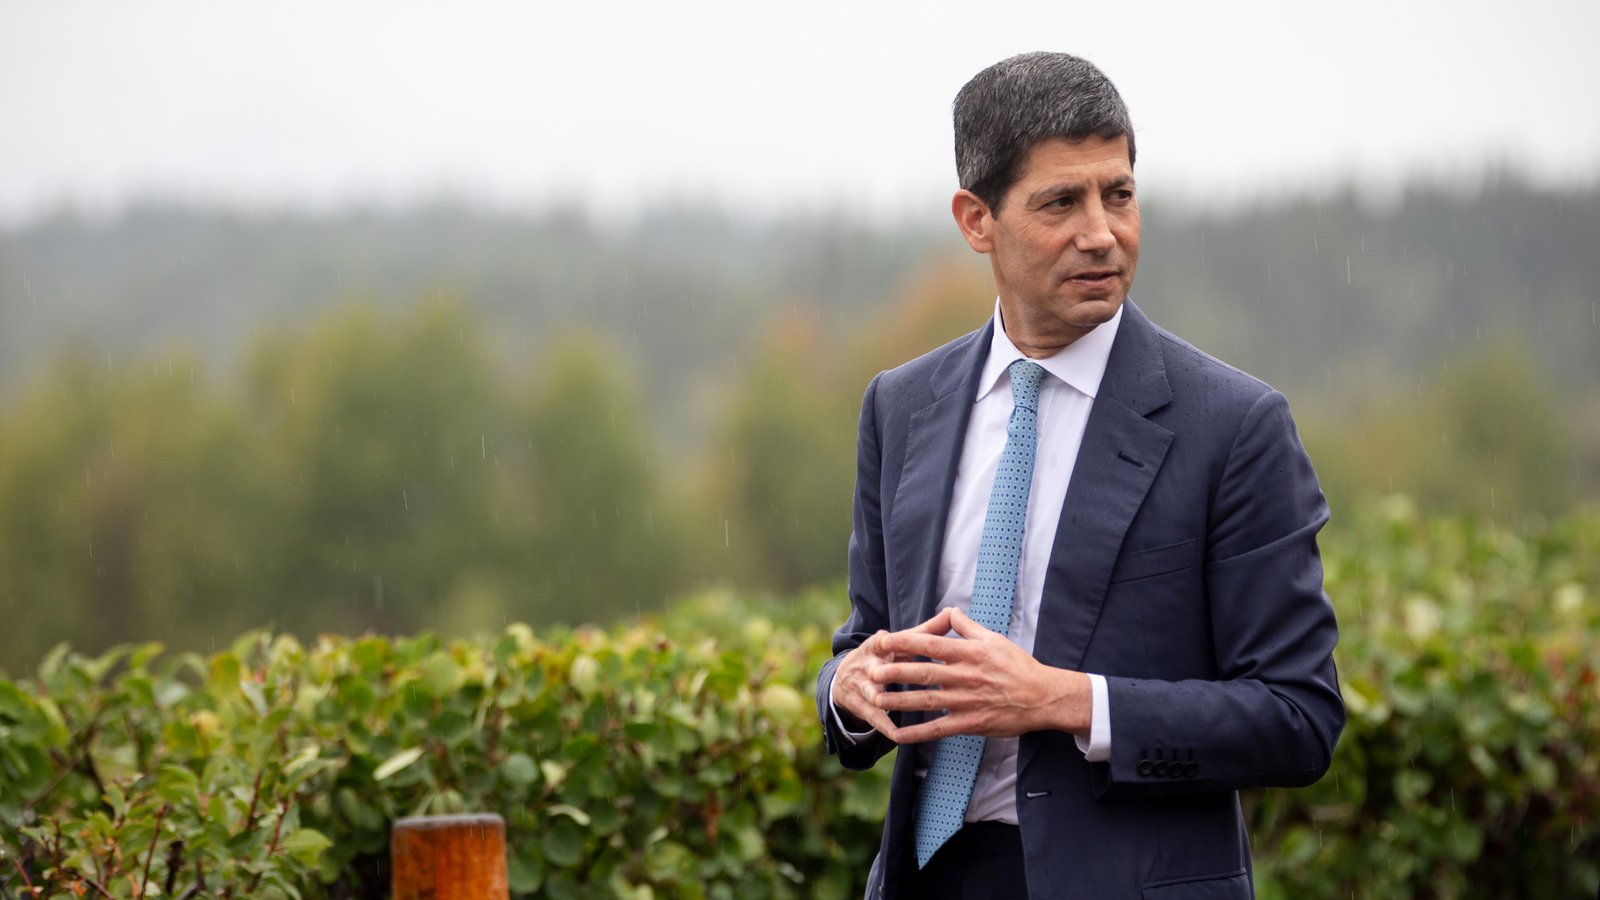
The Federal Reserve is widely expected to lift its short-term interest rate on Wednesday for the first time in three years to combat persistent <a s rate, which currently sits at approximately 3.6%, is not guaranteed because Fed Chair Kevin Warsh does not offer the same signals regarding future policy as his predecessors. Nevertheless, most economists and analysts anticipate a hike following a speech delivered two weeks ago at the Fed’s annual conference in Jackson Hole, Wyoming, where Warsh argued that the central bank had yet to achieve its goal of controlling inflation.
A rate hike would introduce further instability into an already volatile period for financial markets and the broader economy. As recently as March, the Fed had projected a single rate cut for this year. However, with the resurgence of the war in Iran driving up oil and gas prices, inflation is likely to remain above the Fed’s 2% target for a longer duration.
“I don’t see any end to the war in Iran right now,” Kristin Forbes, an economist at MIT’s Sloan School, said. “Given what everyone has been through in the last few years of high inflation, consumers are more sensitive, companies are more sensitive, they raise prices faster … The risks are much more on more persistent inflation than it falling quickly.”
Surging <a s development.
All eyes are on interest rates before the midterms
The potential rate hike arrives just seven weeks before the midterm elections, a period where affordability and high prices have become central issues. Trump has demanded that the Fed lower rates, a policy that is not currently under consideration, and on Sunday the president stated, “the United States is so strong we should be paying the lowest interest rate in the world.”
Trump repeatedly attacked Warsh’s predecessor, Jerome Powell, using harsh <a Hassett said.
Financial markets anticipate that Warsh and the central bank will disregard these warnings. According to futures prices, traders currently assign a 90% probability to a rate hike on Wednesday. That expectation increased following Friday’s inflation report, which indicated that prices remain high and that core inflation, excluding volatile food and energy costs, rose in August compared to the previous month.
Following that report and Warsh’s firm rhetoric on inflation late last month, most economists contend that Warsh must proceed with a rate hike to avoid damaging his credibility with financial markets. Long-term interest rates, such as those for 10-year and 30-year Treasury bonds, could spike if he fails to act, similar to the market reaction following a late July Fed meeting where Warsh failed to convince investors he was prepared to raise rates if necessary.
“At the end of the day the Chair’s repeated stern warnings on inflation intolerance risk institutional credibility absent some action to back it up,” Michael Feroli, an economist at JPMorgan Chase, wrote in a preview of the Fed’s meeting.
A rate increase could raise other questions
Some members of the Fed’s interest-rate setting committee continue to believe that inflation, excluding food and energy, will eventually subside and may not view a rate hike as necessary.
Warsh, however, has not adopted that position. In his Jackson Hole remarks, he noted that recent inflation data “do not tell me that underlying trends have improved,” adding that if such progress is not observed soon, “we have work to do.”
Ironically, by strengthening the Fed’s credibility, a rate hike could help stabilize the long-term interest rates that consumers pay for auto loans and mortgages. Some of the recent increase in mortgage rates likely stemmed from investor concerns that the Fed was not fully committed to curbing inflation. Investors generally require higher yields to hold bonds when inflation is elevated.
Still, if the Fed proceeds with a rate increase on Wednesday, Warsh will face new inquiries: How many additional hikes will the Fed authorize? How effective will these moves be in reducing inflation when much of the pressure stems from oil prices, which the Fed cannot influence? How will the central bank respond if an AI slowdown threatens to dampen the economy, a scenario that would typically prompt a rate cut?
Matthew Luzzetti, chief U.S. economist at Deutsche Bank, noted that it is unusual for the Fed to implement only a single rate hike, as a solitary move would likely have minimal economic impact, suggesting that multiple increases are probable.
He added that the language the Fed uses to describe potential rate hikes on Wednesday could provide insight into its future strategy. For instance, if Warsh indicates that the Fed is reversing the three cuts made in late 2025—a period when the central bank feared rising unemployment—it would signal that two additional hikes are likely forthcoming.
Alternatively, Luzzetti noted that Warsh could frame a hike as a “risk management” measure, where the Fed expects inflation to cool but raises rates to ensure that outcome. That approach could point toward only two total increases.
Warsh has thus far avoided providing such specific guidance. Nevertheless, Wall Street traders are currently pricing in three hikes—scheduled for September, December, and March—according to futures data.