Fidelity and Vanguard recently published long-term stock market projections, and both firms provided a sobering outlook for those planning for retirement: anticipated investment returns are either modest or inflation. These figures stand in contrast to the S&P 500’s historical average of roughly 10% since its inception in 1957.
For retirees, these estimates could result in slower portfolio growth and smaller account balances if these predictions prove accurate or if returns decline further.
What lower stock returns could mean for your retirement savings
Even if you do not actively track the stock market, these projections are worth noting if you hold stocks or equity funds within an IRA or 401(k).
These forecasts imply that your retirement nest egg may grow at a more sluggish pace over the next 10 to 20 years. While market conditions fluctuate, this may be an ideal time to reassess your long-term retirement strategy.
“While the stock market’s trajectory is relatively unpredictable, it is possible that if its returns fall below historical averages, savers could be surprised by the pace of their retirement cushion’s growth,” said Brianna Rodgers, director of investor education at Madison Trust Company. “Those with certain expectations surrounding consistent market growth may see an impact in their savings when compounded over a set number of years.”
Ultimately, most experts agree that the stock market is inherently unpredictable and subject to a variety of unforeseen economic and geopolitical developments.
This does not mean you should ignore these projections; rather, instead of <a Those who are approaching retirement may consider postponing their retirement altogether if returns are markedly lower than anticipated. This can also translate to a complete overhaul regarding investment and withdrawal strategies, as well as overall lifestyle practices," Rodgers said. "Nevertheless, while market projections have the potential to be correct, their outcomes can never be guaranteed."
You might also be overestimating your future expenses. While costs like travel and healthcare often rise in later years, other outlays—such as childcare, housing, and debt obligations—frequently decrease. Additionally, ensure you are accounting for other incomevely you need to save
Make a plan to boost your retirement contributions
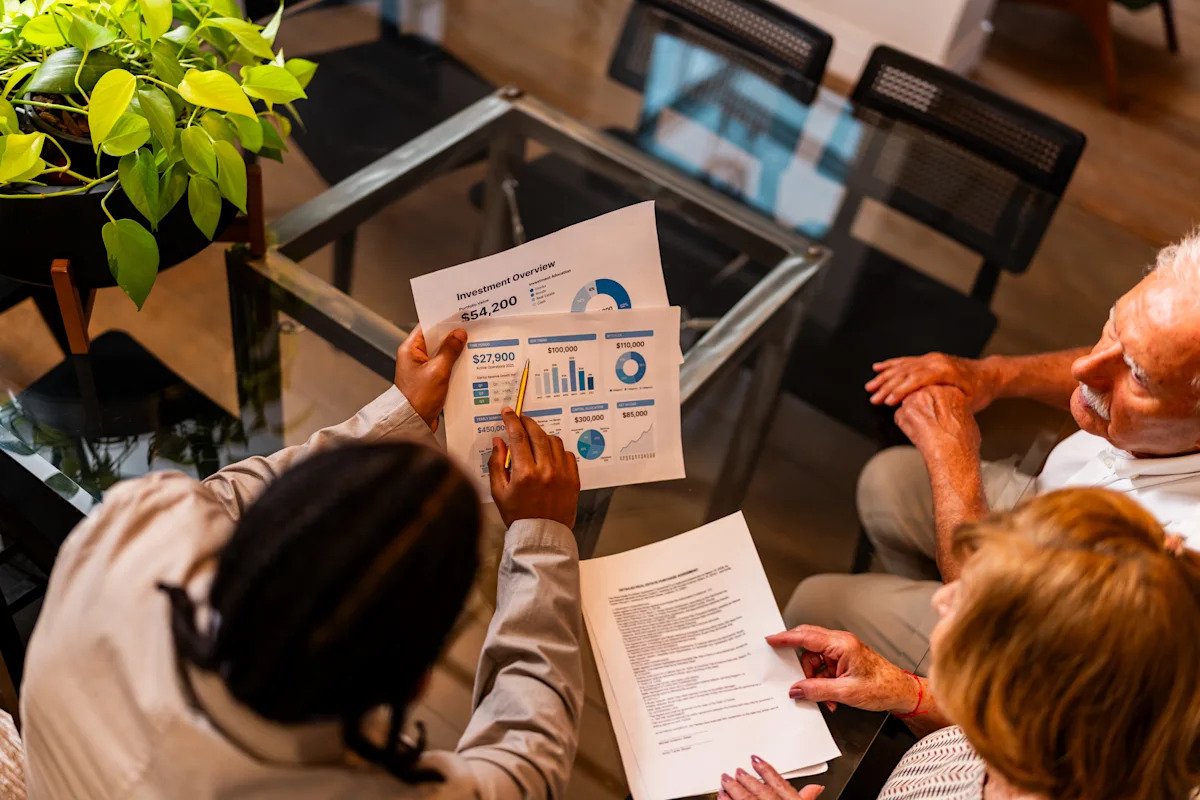
Consistent, early saving is vital. Examine your budget and current contribution levels to see if there is room to increase your savings rate. If you cannot increase contributions immediately, some retirement plans offer automatic escalation features that gradually raise your savings rate over time, often following a raise or performance review. This allows your contributions to grow alongside your income without requiring manual adjustments.
If your employer provides a matching contribution, ensure you are saving enough to capture the full amount. It remains one of the most efficient ways to bolster your savings.
Review diversification and asset allocation regularly
Setting your retirement savings to autopay might feel sufficient, but ignoring your strategy can be expensive.
Your portfolio allocation—the specific mix of investments you hold—influences your long-term returns and your exposure to risk. Make it a habit to periodically review your asset allocation as your goals, risk tolerance, and timeline evolve.
“Observing market forecasts can prove to be beneficial, but it’s often not encouraged to base one’s retirement strategies entirely off predictions,” Rodgers said. “Rather, investors can take this moment to gauge their current saving habits and existing strategies. Consider evaluating whether your portfolio is appropriately diversified and whether any of your present investments put you in a position outside of your risk tolerance.”